
Handyman insurance
Get your handyman business covered with Viz - Certificate of Currency emailed instantly, no fees for paying monthly, and a real person on the phone when you call.
Why do handymen need insurance?
Handyman work takes you into other people's homes and rental properties every day. Drill into a water pipe hidden behind a wall and the repair bill can run well past what the job paid. A Viz public & products liability insurance policy is designed to cover your business for third-party injury and property damage claims arising from your covered handyman business activities.
Real estate agents and property managers will usually ask for a Certificate of Currency as proof your cover is in place before they send you any work.
What can you get covered for as a handyman?
Viz is built for how handymen actually work.
Pay Monthly at no Extra Cost
Cashflow matters. No fees or interest for paying monthly.
One Policy. Multiple Occupations.
Put multiple occupations under one policy and one premium.
Get your Viz Tradie Pass
A Certificate of Currency & insurance hub in your phone's digital wallet.
What can handyman insurance cover?
Third party property damage
If your work accidentally damages a client or other third party's property, public liability insurance can cover the costs you're liable to pay. For handymen, that might mean a ladder slipping on a wet patio and smashing a client's glass sliding door, with a replacement running into the thousands.
Injuries to third parties
If someone is accidentally injured because of your work, public liability insurance can cover the costs you're liable to pay. For a handyman, that could mean a tenant tripping over a power lead you've run down a hallway, with the injury claim running well past the value of the job.
Legal costs
If a claim is made against your business that you may be legally liable to pay, the public liability in your handyman policy can cover the legal costs incurred to defend or settle it. When a client holds you liable for something that you don't necessarily think was your fault, this can come in handy.
Theft of your tools
If you add Tools of Trade cover to your Viz policy, you can insure up to $50,000 of tools and equipment against theft from a securely locked vehicle or building.
Damage to your tools
If you add Tools of Trade cover to your Viz policy, your gear can also be insured for damage from fire, explosion, flood, or a car collision on the way to a job.
What can't handyman insurance cover?
Every insurance policy has exclusions - they keep premiums fair and help reserve cover for genuine, unexpected events. We've listed some of the exclusions that every insured handyman should be aware of.
Injury to your employees
An employee is considered part of your business, not a third party. Workers compensation insurance is typically required if you employ workers, depending on your state or territory, and is designed to cover this risk.
Faulty workmanship
Public liability can cover the damage faulty work causes, but not the cost of redoing the work itself. If a shelf you put up comes off the wall, the cost of putting it back up isn't covered. The repair to the vanity it landed on can be.
Tools theft from open air
If your gear is stolen from an open site or an unlocked car, it won't be covered. Viz's tools cover only applies to theft from a securely locked vehicle or building where there's evidence of forced entry. Cover for open air theft would mean everyone's premium pays for the few who don't lock up - so we chose to exclude it.
Work other than handyman work
Your policy is designed to cover work that would reasonably be expected of a handyman. If you carry out other types of work, like gardening or pressure washing, you'll need to include this in your policy for it to be covered.
Asbestos and silica
Insurers often choose to exclude super high risk situations from their public liability policies. For instance, Viz (as well as most insurers) can't cover you for any work involving asbestos or silica.
The above is not a complete list of the exclusions in your policy. Refer to the policy wording for the full details of your cover.
Here's What Our Customers Have to Say
Rated 4.6 / 5 Excellent
Grab a quote online in 120 seconds
Have a question? Give us a ring on 1300 216 226.
Handyman public liability insurance
If you only need public liability insurance, a Viz handyman policy costs about $445 - $490 a year for $5 million of cover, or about $520 - $575 a year for $10 million, depending on your state's stamp duty. That includes GST, stamp duty and the policy fee. You can also pay monthly at no extra cost - no extra fees or interest. Viz covers sole traders working on their own, and handyman businesses with up to five full-time staff.
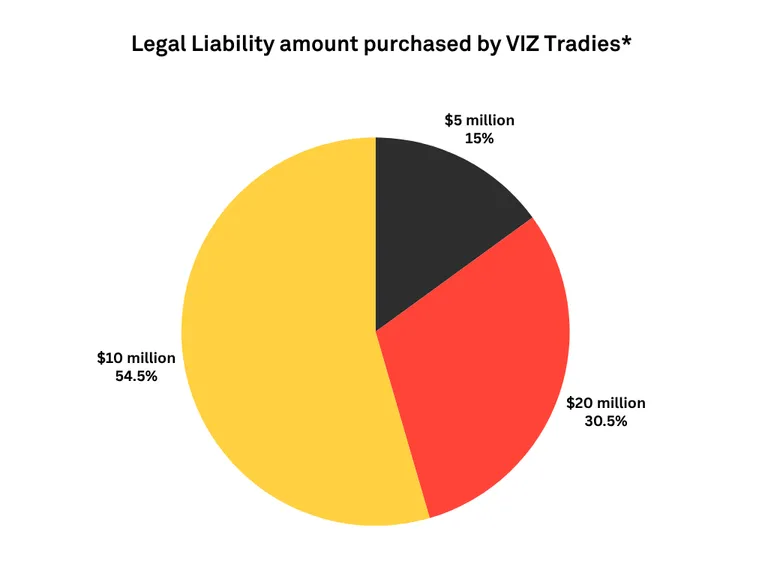
Real estate agents and property managers commonly ask for $10 million of public liability cover, and builders and commercial clients often ask for $20 million. One Viz policy can cover your handyman work for homeowners, agents, property managers and builders, and your Certificate of Currency is emailed to you within seconds.
Do you do more than handyman work?
If your business also does work such as:
- Gardening, landscaping and lawn mowing
- Guttering and fascia board installation and maintenance
- Pressure washing
- Carpentry and joinery
You can add these occupations to the same policy and only pay one premium, which is set by the highest priced trade.
What goes into a handyman insurance policy?
Build your policy from the three cover options that Viz offers.
Public & products liability insurance
Why you might need it
Public & products liability insurance is the part of your policy that's designed to respond if your work injures someone or damages their property. For handymen, that can mean a client's TV cracking while you mount it on their wall, or damage caused by a shelf you put up weeks ago.
It's also something you'll usually need before you start. Real estate agents, property managers and commercial clients will typically ask for a Certificate of Currency as proof your cover is in place.
How it works
You can choose from $5m, $10m or $20m of public liability cover. This is the most you can be paid out for claims within a policy period.
Depending on the work you take on, you may need a minimum level - many builders and commercial sites require $10 million or $20 million before you can start. With Viz, your Certificate of Currency is emailed to you instantly after you take out a policy, so you can provide your docs straight away.
Tools & equipment insurance
Why you might need it
Your tools are how the work gets done and how you get paid. Without your drills and angle grinder, jobs stop. If you include Tools of Trade cover on your policy, your gear can be covered if it's stolen or damaged by an insured event, so you can repair or replace it and get back to work.
How it works
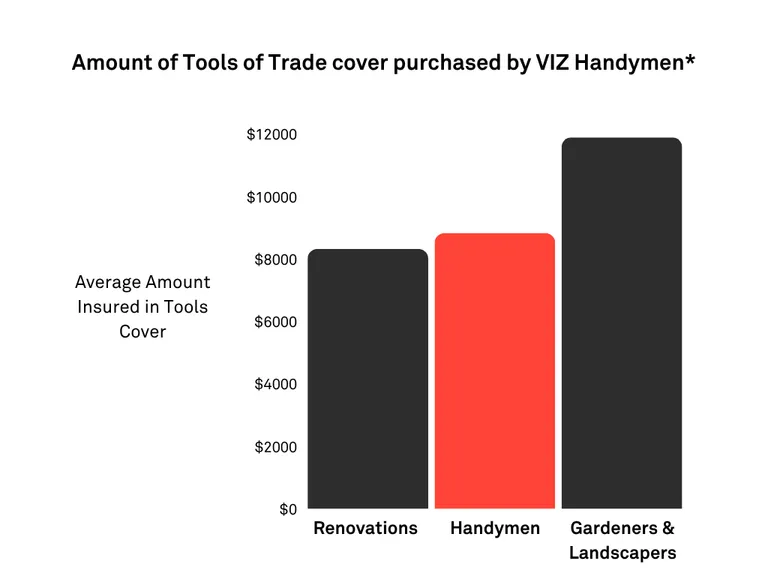
Tools and equipment cover is an optional extra you can add to your policy. Choose from $5,000, $10,000 or $20,000 of cover for general tools and equipment worth less than $2,500 per item. Higher-value gear - like a nail gun or a trailer - can be listed individually as specified items. You can add up to $30,000 of specified items, giving you up to $50,000 in total cover. You can always add or remove tools from your policy once it is in place.
Tax audit insurance
Why you might need it
The ATO can audit any business, handyman businesses included, at their discretion - whether or not there's been a mistake. Some are selected at random, others based on tax lodgements. For someone running their own handyman business, a tax audit can mean dealing with accountants and professional fees while responding to the ATO. If you choose to include tax audit cover, it can cover those costs and help protect your cashflow.
How it works
Tax audit cover is optional and can be added or removed from your policy at any time. It provides $50,000 of cover if selected, with the option to choose an excess that suits you.
How much does handyman insurance cost?
Choose your public liability limit, and add tools and tax audit cover if you want them. Here are four examples of how a policy could look.
What might a handyman's claim look like?
Matt, from Matt's Home Maintenance
Matt accidentally spilt water across a client's floor while he was working, soaking a sisal rug and the floorboards underneath. The rug couldn't be washed or steam cleaned, and the floorboards had to be sanded back and re-stained. The claim came to just over $5,800, which was covered under his public liability insurance.
Sam, from Odd Job Sam
Sam was fitting a new wall cabinet when he drilled into a copper pipe hidden in the wall. Water from the pipe damaged the new cabinet. The claim came to just over $1,100, which was covered under his public liability insurance.
Kirsty, from Kirsty's Property Maintenance
Kirsty's business ute was broken into and her tools were stolen. The stolen gear came to around $3,600, which was covered under her tools of trade insurance.
What happens in a handyman's claim process?
Claim time is when your insurance needs to deliver, especially with a builder or homeowner waiting on you. At Viz, claims are managed by our specialist claims partner, Sedgwick. Their role is to guide you through your claim and help you get back to your pre-loss position as quickly as possible, with minimal disruption.
1.
Lodge your claim
2.
A representative will get in touch
3.
Claim assessment
Nail down your cover with Viz Insurance.
Rather speak to someone? Call us on 1300 216 226.
Frequently asked questions
A Viz handyman insurance policy is designed to cover the work reasonably expected of a handyman, like general repairs and maintenance, flat-pack furniture assembly, drilling and hanging TVs and shelves, and painting and patching. OSCA, the Australian Bureau of Statistics' national occupation classification, is Viz's reference for the activities that sit clearly within the trade, under handyperson (899331). If you take on painting-only contracts, it may be worth adding painting as its own occupation. Licensed work, like plumbing, electrical or gas fitting, needs the applicable licence. If you're not sure whether a job fits, give us a call on 1300 216 226 or email hello@vizinsurance.com.au.
Handyman insurance with Viz costs about $37 - $41 per month for $5 million of public liability cover, or about $44 - $48 per month for $10 million, depending on your state's stamp duty. Your premium is based on your occupation, your cover limit, the number of workers in your business, your state and any optional covers and excess you choose. Turnover isn't part of the price. Paying monthly comes at no extra cost compared with paying annually - no extra fees or interest. Get a quote in 2 minutes to see your price.
It usually depends on who you work for. Viz offers $5 million, $10 million or $20 million of public liability cover, and the limit is often set by the client or the contract. Real estate agents and property managers commonly ask for $10 million, and builders and commercial clients often ask for $20 million.
There's no height restriction on a Viz handyman policy, so ladder work and second-storey jobs can sit within your cover. Guttering and fascia board installation and maintenance can be added to your policy as another occupation.
It can. If you accidentally damage a client's TV while mounting it in their home, public liability can cover it as damage to third party property. If you take an item away to work on it, cover for damage to that item is limited to $250,000, and the cost of redoing faulty work isn't covered.
Yes. Gardening and outdoor maintenance can be added to your Viz policy as the 'Gardening, landscaping and lawn mowing' occupation. Pressure washing, and guttering and fascia board installation and maintenance, can each be added as another occupation too. You pay one premium, set by the highest priced occupation category, and you can add up to two occupation categories online, or more by phone or email.
Public liability insurance is expected for handymen working in rental properties and commercial premises. Real estate agents, property managers and commercial clients typically ask for a current Certificate of Currency before work starts. Viz provides handyman cover up to $20 million.
Handymen working for a builder can be covered, as on any Viz policy. If you have subcontractors working under you, Viz can't cover injury to them - we do this to help avoid conflict with workers compensation requirements.
Once you take out a policy with Viz, your Certificate of Currency and other documents are emailed to you within seconds. You can also sign up for the Viz Tradie Pass, which keeps an up-to-date copy on your phone whenever you need it.
Things to know
* Viz charges an annual $49.50 Policy Fee payable in addition to your premium. If you pay monthly, this will be charged along with your first monthly payment. The policy examples above are an indication only and are based on businesses with one employee, an excess of $500 and stamp duty charges for the state shown. Your premium will be calculated based on the information you provide to us during the insurance application process.
The claim examples above are real claims, however the personal and business names used in each example have been changed for privacy. Every claim is different and is assessed on its individual circumstances and policy coverage.
You can add up to two occupation categories on to your quote online. Some of these categories contain two different trades, e.g. 'Handyman, Landscaping, Mowing and Gardening'. If you need additional business activities covered or have any questions about our policies, give us a call on 1300 216 226 or email us at hello@vizinsurance.com.au.