
Landscapers Insurance
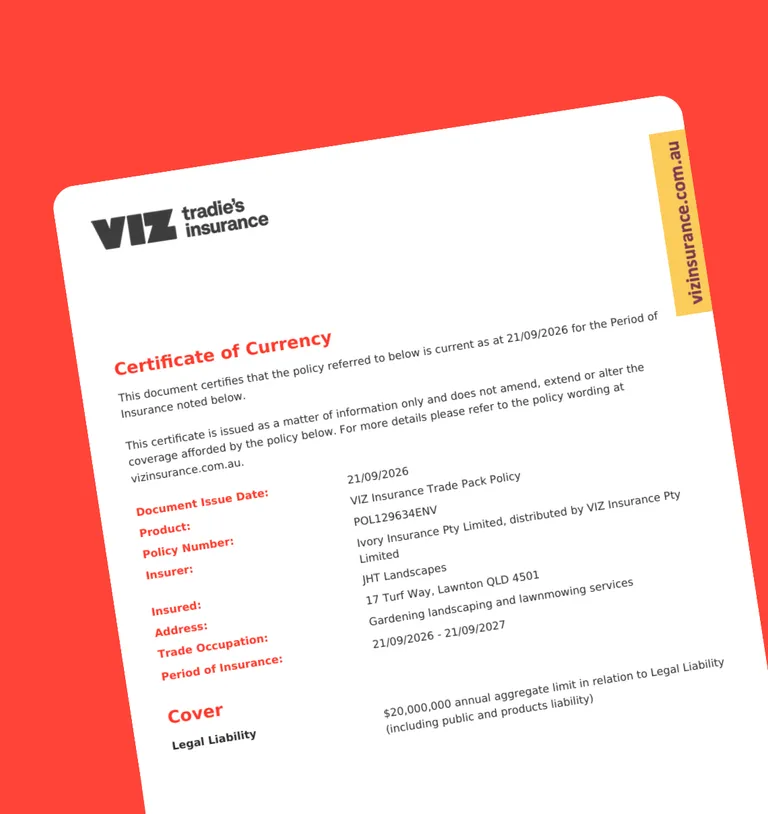
Retaining walls, paving, planting and the mowing round in between all sit under one occupation. Certificate of Currency emailed instantly, and no extra cost to pay monthly.
Why do landscapers need insurance?
Landscaping puts machinery, excavation and tonnes of material inside the boundary of your client's home. A trench catches a service line, a machine clips a downpipe, a pallet of pavers goes through a driveway. A Viz public & products liability insurance policy is designed to cover your business for third-party injury and property damage claims arising from your covered landscaping business activities.
Cover is also part of the paperwork your clients ask for up front. Builders and principal contractors on new builds and renovations will usually want a Certificate of Currency, often at a $10 million or $20 million limit, before your first delivery turns up.
What can you get covered for as a landscaper?
Viz is built for how landscapers actually work.

Pay Monthly at no Extra Cost
Cashflow matters. No fees or interest for paying monthly.
One Policy. Multiple Occupations.
Put multiple occupations under one policy and one premium.
Get your Viz Tradie Pass
A Certificate of Currency & insurance hub in your phone's digital wallet.
Pay Monthly at no Extra Cost
Cashflow matters. No fees or interest for paying monthly.
One Policy. Multiple Occupations.
Put multiple occupations under one policy and one premium.
Get your Viz Tradie Pass
A Certificate of Currency & insurance hub in your phone's digital wallet.
What can landscapers insurance cover?
Third party property damage
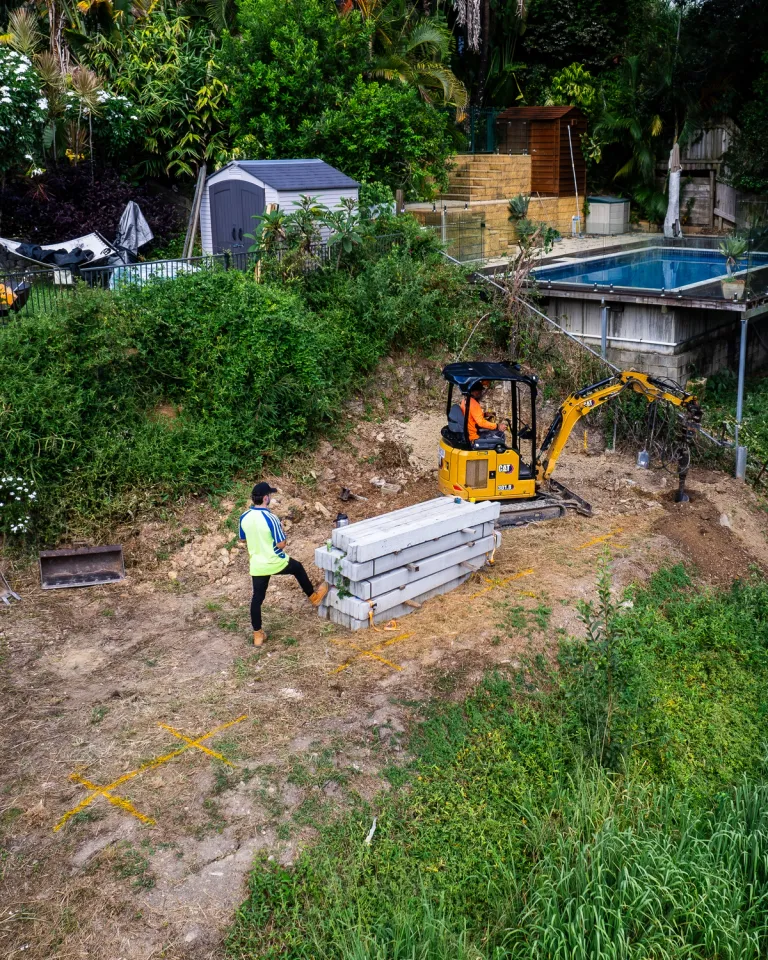
If your work accidentally damages someone else's property, public liability insurance can cover the costs you're legally liable to pay. For landscapers, that might mean a machine bucket swinging into a client's garage door while you position retaining wall blocks, and a replacement running into the thousands.
Injuries to third parties
Injuries to third parties
If someone is accidentally injured because of your work, public liability insurance can cover the costs you're legally liable to pay. For landscapers, that might mean a client's visitor stepping into an irrigation trench you've opened but not yet backfilled, with the injury claim running well past the value of the job.
Legal costs
If a claim is made against your business that you may be legally liable to pay, the public liability in your landscaping policy can cover the legal costs incurred to defend or settle it.
When a client holds you liable for something that you don't necessarily think was your fault, this can come in handy.
Theft of your tools
Theft of your tools
If you add Tools of Trade cover to your Viz policy, you can insure up to $50,000 of tools and equipment against theft from a securely locked vehicle or building.
Damage to your tools
Damage to your tools
If you add Tools of Trade cover to your Viz policy, your gear can also be insured for damage from fire, explosion, flood, or a car collision on the way to a job.
Loading and unloading vehicles
Viz's public liability insurance can cover damage to third party property that happens while loading or unloading from a registered vehicle during your business activities. For landscapers, that might mean a plate compactor rolling back off the ramp into a car parked behind the trailer.

What can't landscapers insurance cover?
Every insurance policy has exclusions - they keep premiums fair and help reserve cover for genuine, unexpected events. We've listed some of the exclusions that every insured landscaper should be aware of.
Injury to your employees
An employee is considered part of your business, not a third party. Workers compensation insurance is typically required if you employ workers, depending on your state or territory, and is designed to cover this risk.
Faulty workmanship
Faulty workmanship
Public liability can cover the damage faulty workmanship causes. It can't cover the cost of doing that work again. If a paved path is laid badly and has to be lifted and relaid, the cost of redoing it isn't covered. If that same job cracked a rendered wall beside it, the cost of that damage can be covered.
Tools theft from open air
Tools theft from open air
If your gear is stolen from an open site or an unlocked car, it won't be covered. Viz's tools cover only applies to theft from a securely locked vehicle or building where there's evidence of forced entry. Cover for open air theft would mean everyone's premium pays for the few who don't lock up - so we chose to exclude it.
Work other than landscaping
Your policy is designed to cover work that would reasonably be expected of a landscaper. If you carry out other types of work, like carpentry or earthmoving, you'll need to include this in your policy for it to be covered.
Excavation and underground work
We can't cover personal injury or damage to third party property from underground work beyond 3.5m deep.
For work up to 3.5m in depth, relevant regulations and Australian Standards must be followed, including searches for underground services.
For landscapers, that means searching before you dig footings, irrigation trenches or postholes.
The above is not a complete list of the exclusions in your policy. Refer to the policy wording for the full details of your cover.
Here's what our customers have to say
Rated 4.6 / 5 Excellent
Grab a quote online in 120 seconds
Have a question? Give us a ring on 1300 216 226.
What landscaping work is covered?
A Viz landscaping policy is designed to cover the work reasonably expected of a landscaper. For the full list, see the covered business activities for gardening, lawn mowing and landscaping.
If you take on concreting or structural building work outside of a landscaping context, you can add the relevant occupation to your policy.
Landscaping, gardening and mowing under one occupation
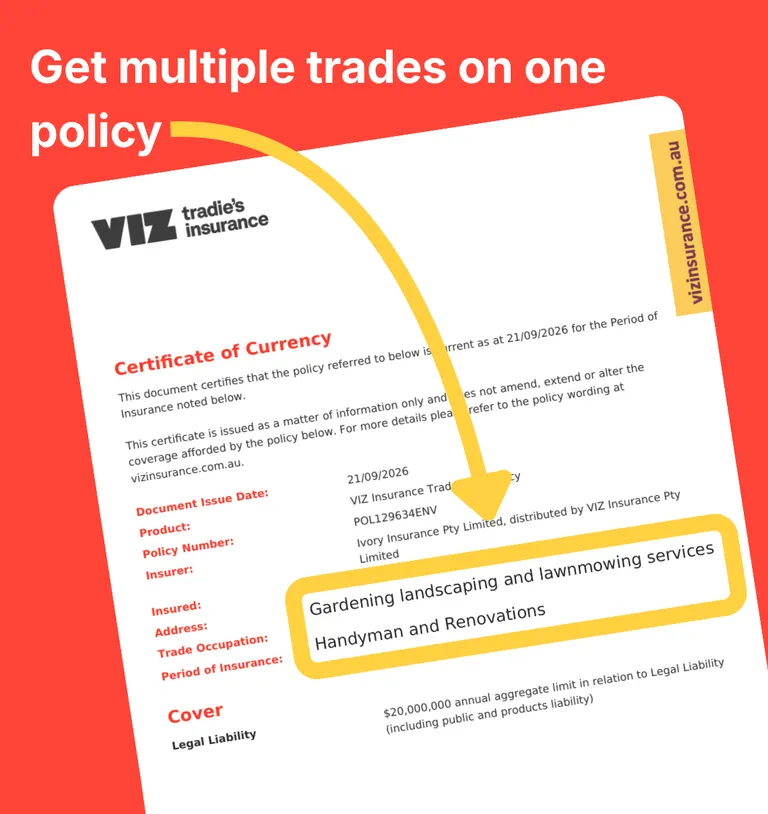
Most landscaping businesses carry some maintenance work - a mowing round between builds, or ongoing garden upkeep for a client whose yard you put in last year. On a Viz policy that is not considered a second occupation. Landscaping, gardening and lawn mowing sit in one occupation category, on one premium, with all three printed on your Certificate of Currency.
You can add up to two occupation categories on your quote online, so you've got a second slot for work that belongs to in different trade. If your business also takes on:
- ● Concreting
- ● Earthmoving and excavation
- ● Handyman and general maintenance
- ● Renovation work
You can add these occupations to the same policy and only pay one premium, which is set by the highest priced trade.
What goes into a landscapers insurance policy?
Every policy starts with public and products liability. Tools of Trade and tax audit cover are optional, and you can add or drop either once the policy is in place.
Public & products liability insurance
Why you might need it
Public & products liability is the part of your cover designed to protect you if your work accidentally injures a third party or damages their property. For landscapers, that can mean a machine catching a client's garage door on the way past, or a retaining wall you finished weeks ago giving way and taking a neighbour's fence with it.
It is also the first thing a builder or a strata manager asks for. Most will want to see a current Certificate of Currency, and many set a minimum limit, before they let you book a start date.
How it works
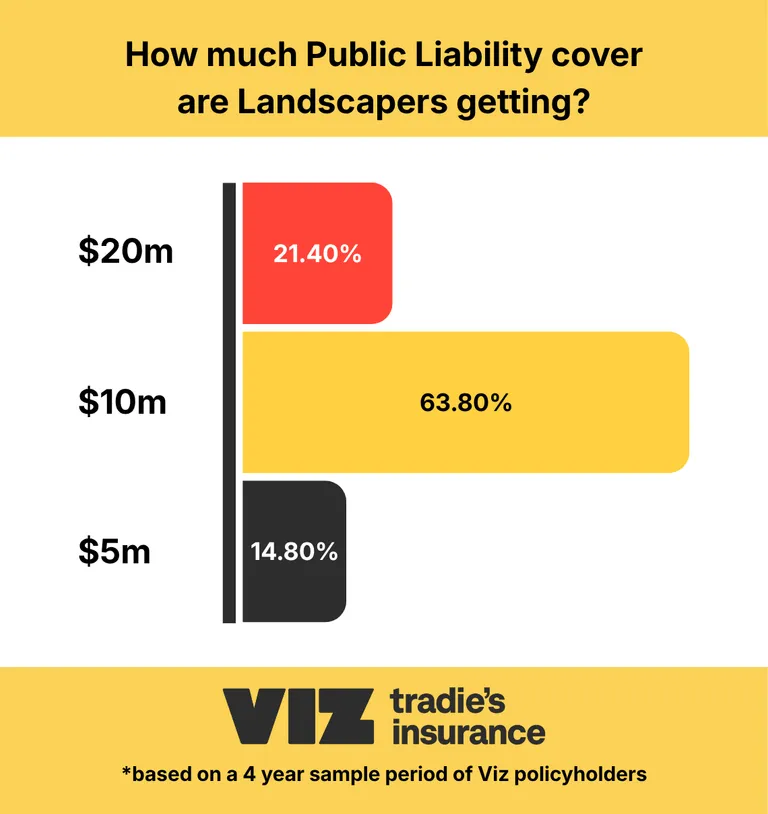
You can choose from $5m, $10m or $20m of public liability cover. This is the most you can be paid out for claims within a policy period.
Depending on the work you take on, you may need a minimum level - many builders and commercial sites require $10 million or $20 million before you can start. With Viz, your Certificate of Currency is emailed to you instantly after you take out a policy, so you can provide your docs straight away.
Tools & equipment insurance
Why you might need it
Your gear is how the work gets done and how you get paid. Turf cutters, plate compactors, post-hole diggers, brushcutters - without them, jobs stop. If you include Tools of Trade cover on your policy, your gear can be covered if it's stolen or damaged by an insured event, so you can repair or replace it and get back to work.
How it works
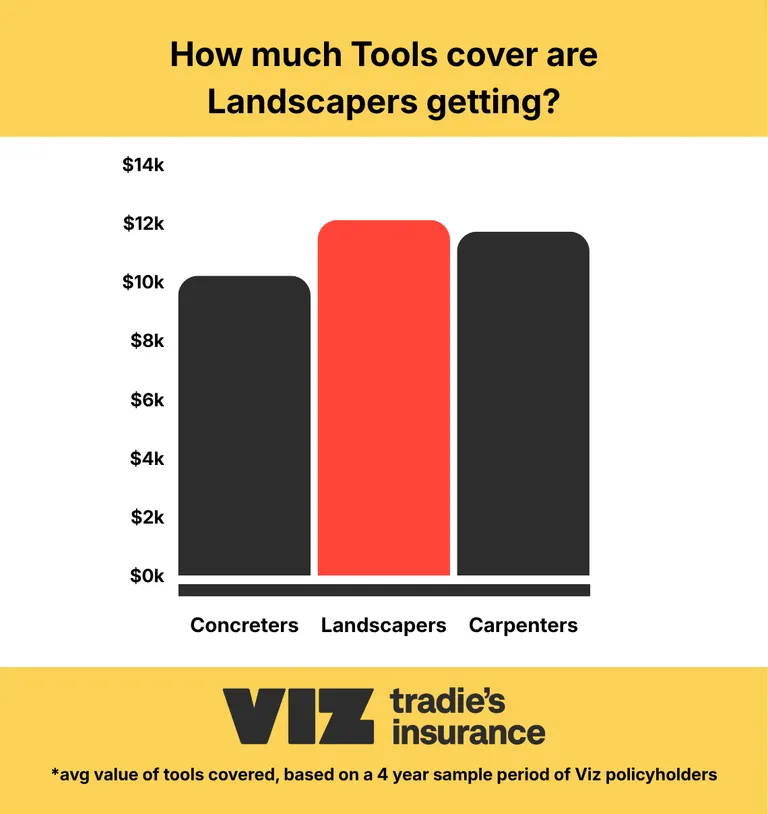
Tools of Trade cover is an optional extra you can add to your policy. Unspecified Items are a pool - $5,000, $10,000 or $20,000 - for items worth up to $2,500 each. For landscapers that is the everyday gear: brushcutters, blowers, hedge trimmers and hand tools.
If you have higher-value items - like a plate compactor or a turf cutter - these can be listed individually as specified items. You can add up to $30,000 of specified items, giving you up to $50,000 in total cover. You can always add or remove tools from your policy once it's in place.
If you want cover for tools and equipment that you are hiring, simply specify them on the policy with their description and value.

Tax audit insurance
Why you might need it
An ATO audit doesn't need a mistake to trigger it. Some businesses are picked at random, others because of what their lodgements look like. If you do your own books, an audit means accountant time and professional fees while the ATO works through it. Tax audit cover, if you include it, can cover those costs so the bill doesn't come out of your cashflow.
How it works
Tax audit cover is optional and can be added or removed from your policy at any time. It provides $50,000 of cover if selected, with the option to choose an excess that suits you.
What does a landscaper's claim process look like?
Claim time is when your insurance needs to deliver, especially with a builder or homeowner waiting on you. At Viz, claims are managed by our specialist claims partner, Sedgwick. Their role is to guide you through your claim and help you get back to your pre-loss position as quickly as possible, with minimal disruption.
1.
Lodge your claim
Fill out the claim form, call the claims team on 1300 850 491, or send the details to vizclaims@au.sedgwick.com. You'll get confirmation once your information has been received.
2.
A representative will get in touch
A Sedgwick representative will be in touch, likely to gather more detail about your claim. That can include a police report, proof of ownership, and an account of what happened, when and where.
3.
Claim assessment
Once the claims team has everything they need from you, they aim to make a decision within 1 to 10 business days, depending on the complexity of the claim.
Lay the groundwork with Viz Insurance.
Rather speak to someone? Call us on 1300 216 226.
Frequently asked questions
Landscapers insurance with Viz starts at about $3 a month for $5 million of public liability cover, or about $45 a month for $10 million. Your exact premium depends on the limit you choose, the number of workers in your business, and your state or territory. Paying monthly costs no more than paying annually - no fees, no interest. It takes about 2 minutes to run a quote and see your price.
Yes. Building hardscape structures - retaining walls, paved paths, pergolas, ponds, fences and garden structures and furniture - is considered reasonably expected of a landscaping business. Soft landscaping such as planting out, turf laying and garden bed construction are covered business activities as well.
Your policy is designed to cover third party property damage that arises from your landscaping work, but underground work carries conditions. Underground work beyond 3.5m deep isn't covered. For underground work taking place shallower than that, you can be covered, but need to follow the relevant regulations and Australian Standards, and that includes searching for underground services before you dig.
No. Landscaping, gardening and lawn mowing are a single occupation category at Viz. Pick 'gardening, landscaping and lawn mowing' at quote and the maintenance side of your work is included on the same premium, with all three shown on your Certificate of Currency.
Viz uses the ABS Occupation Standard Classification for Australia (OSCA) definitions as a guide to what sits inside landscaping, and you can search for your trade with the Trade Activity Checker. Work that isn't listed on OSCA isn't automatically excluded if it's reasonably expected of a landscaper. If you aren't sure about a particular business activity, get in touch via hello@vizinsurance.com.au or 1300 216 226.
Ivory Insurance Pty Limited underwrites Viz policies that started on or after 1 July 2025. Viz Insurance Pty Ltd holds an Australian Financial Services Licence (AFSL 494857) and binds and manages the policy under a binding authority with the insurer. Claims are handled by Sedgwick, who have been managing claims for more than 50 years.
Once you take out a policy with Viz, your Certificate of Currency and other documents are emailed to you within seconds. You can also sign up for the Viz Tradie Pass, which keeps an up-to-date copy on your phone whenever you need it.
There's no law that makes it compulsory. In practice it decides whether you get the job - residential clients, strata managers and commercial builders ask for it before work starts. If you subcontract to a builder or a larger landscaping outfit, the contract will usually name a minimum limit, most often $10 million or $20 million. Viz offers landscapers limits up to $20 million.
Mobile plant under 1.5 tonnes that isn't normally registered for road use can be covered under the tools section of your policy, as long as it's listed as a specified item. Machines at or above 1.5 tonnes sit outside the tools section. The size of the plant you operate doesn't change your public liability cover.
Things to know
Monthly Payments vary by state due to state-based stamp duty charges. Viz charge an annual $49.50 Policy Fee payable in addition to your premium. The prices shown are based on selecting a $500 excess and are an indication only. Your premium will be calculated based on the information you provide to us during the insurance application process.
You can add up to two occupation categories on to your quote online. Some of these categories contain two different trades, e.g. 'Landscaping and renovations'. If you need additional business activities covered or have any questions about our policies, give us a call on 1300 216 226 or email us at hello@vizinsurance.com.au.