
Gardening and Lawn Mowing Insurance
Get your gardening or lawn mowing business covered with Viz - instant Certificate of Currency, monthly payments at no extra cost, and an Australian team on the phone.

Why do Gardeners need insurance?
Gardening and mowing work puts you around other people's property every day, and one mistake can cost more than the job ever paid. Insurance is there to help cover that financial hit when something goes wrong.
One in seven claims Viz pays is a gardening or lawn mowing business flicking up a stone and breaking glass - the most common claim we see.
Insurance is also something clients ask for before you start. Strata managers and real estate agents will often ask for a Certificate of Currency as proof your cover is in place.
What cover can you get for your gardening business?
Viz is built for how gardeners actually work.

Pay Monthly at no Extra Cost
Cashflow matters. No fees or interest for paying monthly.
One Policy. Multiple Occupations.
Put multiple occupations under one policy and one premium.
Get your Viz Tradie Pass
A Certificate of Currency & insurance hub in your phone's digital wallet.
Pay Monthly at no Extra Cost
Cashflow matters. No fees or interest for paying monthly.
One Policy. Multiple Occupations.
Put multiple occupations under one policy and one premium.
Get your Viz Tradie Pass
A Certificate of Currency & insurance hub in your phone's digital wallet.
What can Gardening and Lawn Mowing Insurance cover?
Third party property damage
Third party property damage
If you accidentally damage a client's or other third party's property while working, public liability insurance can cover the costs you're required to pay. For gardeners, that might mean a stone thrown from under the mower deck shattering a glass sliding door, and a repair bill running into the thousands.
Injuries to third parties
Injuries to third parties
As well as being able to cover property damage to third parties, public liability insurance can also cover the costs associated with accidentally injuring a third party (such as a client or passerby).
Legal costs
Legal costs
If a claim is made against your business that you may be legally liable to pay, the public liability in your gardening policy can cover the legal costs incurred to defend or settle it. This is particularly useful if a client alleges that you damaged their property, whether or not you actually did.
Theft of your equipment
Theft of your equipment
You can add up to $50k of Tools & Equipment cover to your Viz policy, and cover your mowers, trailer, whipper snippers, blowers and hedge trimmers from theft from a securely locked vehicle or building.
Damage to your equipment
Damage to your equipment
If you add Tools & Equipment cover to your Viz policy, you can cover your gear for damage from flood, fire, a car collision, or explosion.
Loading and unloading vehicles
Loading and unloading vehicles
Viz's public liability insurance can cover you for damage to the property of a third party that happens during the loading and unloading of registered vehicles.

What can't Gardening and Lawn Mowing Insurance cover?
Every insurance policy has exclusions - they keep premiums fair and help reserve cover for genuine, unexpected events. We've listed some of the exclusions that every insured gardener should be aware of.
Injury to your employees
Injury to your employees
An employee is considered part of your business, not a third party. Workers compensation insurance is typically required to cover the risk of employees getting injured, although exact requirements vary by state.
Faulty workmanship
Faulty workmanship
While public liability can cover the damage faulty work causes, it can't cover the cost of redoing the job itself. For example, if a hedge is cut back too hard and the plants have to be replaced, the cost of replanting isn't covered. But if that same job damaged property other than the plants - like a rendered wall or a light fitting - the cost of that damage could be covered.
Equipment theft from open air
Equipment theft from open air
If your gear is stolen from an open site or an unlocked car, it won't be covered. Viz's tools cover only applies to theft from a securely locked vehicle or building where there's evidence of forced entry. Cover for open air theft would mean everyone's premium pays for the few who don't lock up - so we chose to exclude it.
Work other than gardening, lawn mowing and landscaping
Work other than gardening, lawn mowing and landscaping
Your policy is designed to cover work that would reasonably be expected of a gardener. If you carry out other types of work, like handyman work or pressure washing driveways, you'll need to include this in your policy for it to be covered.
Viz uses the OSCA occupation definitions as a guide to what sits inside the trade. Work that isn't on those lists isn't automatically excluded if it's reasonably expected of the trade.
Tree felling and lopping over 3.5 metres
Tree felling and lopping over 3.5 metres
Insurers often exclude higher risk work from their public liability policies. Viz can't cover you for felling or lopping a tree taller than 3.5 metres. The 3.5 metre limit applies to felling and lopping only - pruning, hedging and trimming are a normal part of the trade at any height.
The above is not a complete list of the exclusions in your policy. Refer to the policy wording for the full details of your cover.
Here's What Our Customers Have to Say
Rated 4.6 / 5 Excellent
Grab a Quote Online in 120 seconds
Have a question? Give us a ring on 1300 216 226.
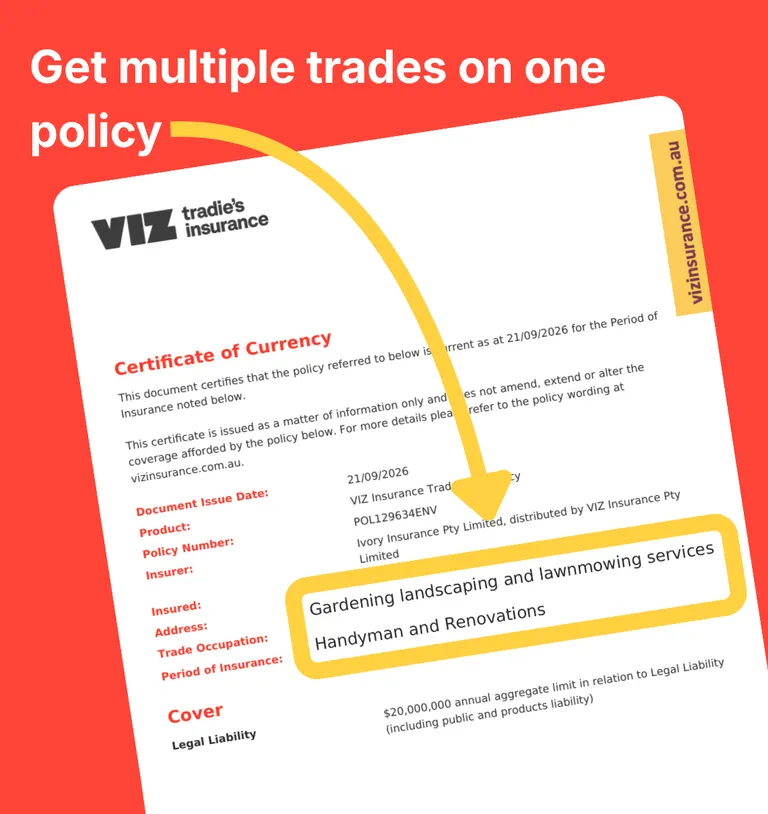
Cover for gardening, lawn mowing and landscaping
Gardening, lawn mowing and landscaping are treated as one occupation on a Viz policy. Select 'Gardening, landscaping and lawn mowing' when you get a quote and that whole spread of work sits under one policy, with all three listed on your Certificate of Currency.
If your business also takes on contracts solely for other services, such as:
- ● Handyman and general maintenance
- ● Pressure washing and exterior cleaning
- ● Window or gutter cleaning
- ● Domestic cleaning
You can add these occupations to the same policy and only pay one premium, which is set by the highest priced trade.
What goes into a Gardening and Lawn Mowing Insurance policy?
Build your policy from the three cover options that Viz offers.
Public & Products Liability Insurance
Why you might need it
Public & products liability is the part of your cover that's designed to protect you if your work causes injury to someone else or damage to their property. For gardening and lawn mowing businesses, damage to a third party's property might mean a stone flicked up from under the mower shattering a client's window.
It's also something you'll often need before you can start a contract. Strata managers, real estate agents and commercial clients will typically ask for a Certificate of Currency as proof your cover is in place.
How it works
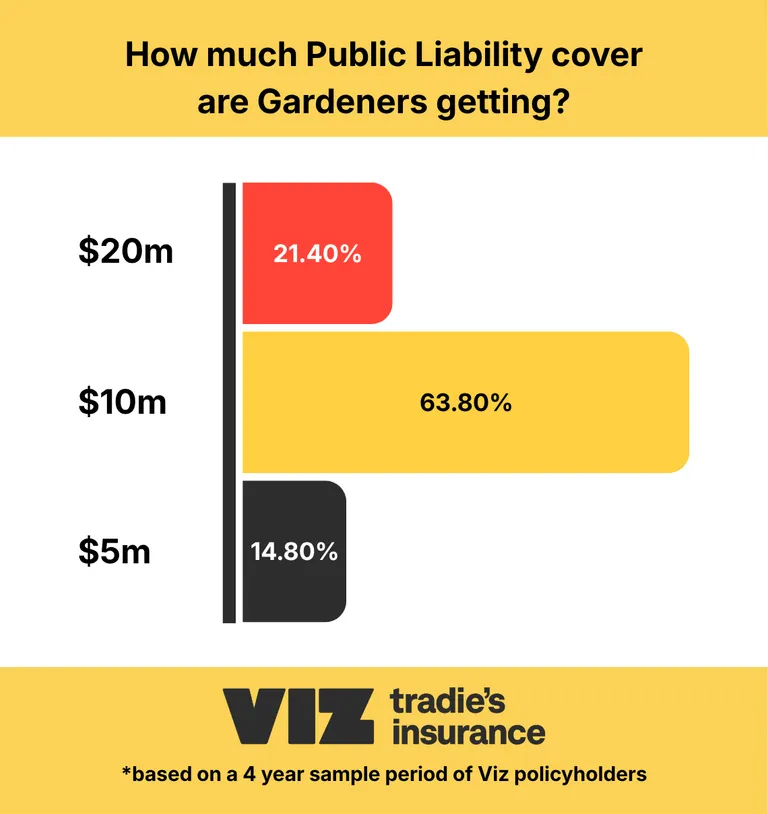
Public and products liability is the foundation of your cover and is included in every policy. You can choose from $5 million, $10 million or $20 million of public and products liability. This is the maximum amount that can be paid for claims within a policy period.
With Viz, your Certificate of Currency is emailed to you instantly after you take out a policy, so you can provide your docs straight away.
Tools & Equipment Insurance
Why you might need it
If you run a gardening or lawn mowing business, your equipment is what gets the job done and gets you paid. Without it, business can grind to a halt.
If you choose to include Tools & Equipment cover, it's designed to help protect your gear if it's stolen or damaged by an insured event, so you can repair or replace it and get back to work.
How it works
Tools & Equipment cover is an optional extra you can add to your policy.
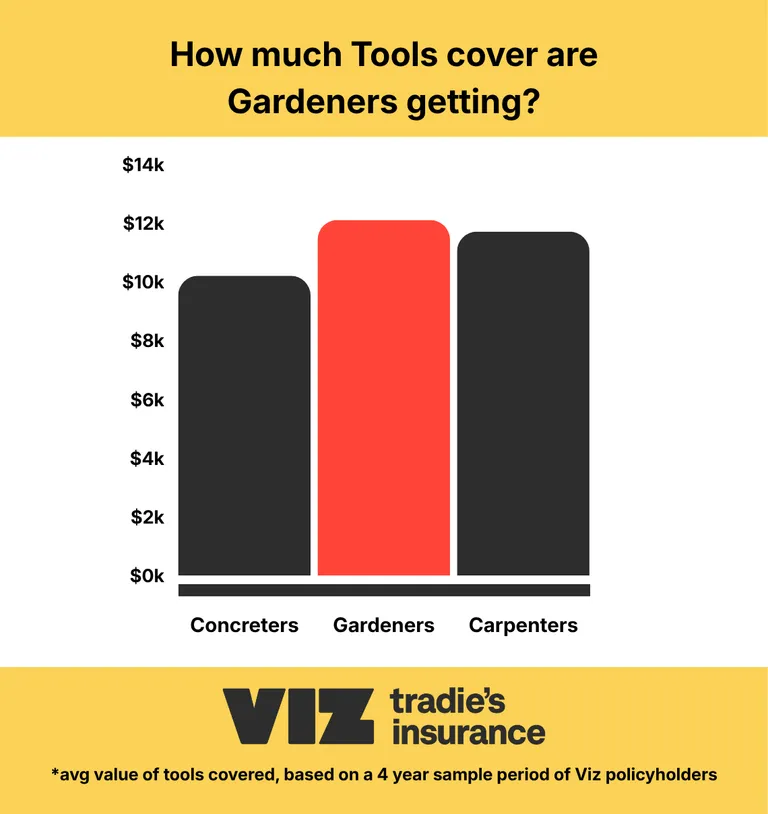
Choose from $5,000, $10,000 or $20,000 of cover for tools and equipment worth less than $2,500 per item. For gardeners, that could include push mowers, whipper snippers, blowers, edgers and hedge trimmers.
If you have higher-value items - like ride-on mowers or trailers - these can be listed individually as specified items. You can add up to $30,000 of specified items, giving you up to $50,000 in total cover. You can always add or remove tools from your policy once it's in place.

Tax Audit Insurance
Why you might need it
The ATO can audit any business, including gardening and lawn mowing businesses - whether or not there's been a mistake or issue. Some are selected at random, while others are reviewed based on their tax lodgements.
For someone running their own gardening or lawn mowing business, a tax audit can mean dealing with accountants and professional fees while responding to the ATO. If you choose to include tax audit cover, it's designed to help cover those costs and protect your cashflow.
How it works
Tax audit cover is optional and can be added or removed from your policy at any time. It provides $50,000 of cover if selected, with the option to choose an excess that suits you.
What might a gardeners claim process look like?
Reece, from Reece's Mowing and Yard Care
Reece was whipper snipping along a client's fence when a stone was flicked into the glass sliding door beside him and the entire pane shattered. The claim came to just under $1,800.
Nathan, from Northline Mowing
Nathan parked on a slope to finish a job. On the way back to the trailer the mower got away from him, rolled down the hill and hit a neighbour's car. Nathan's public liability policy stepped in to cover the $4,000 which was claimed against his business.
Steph, from Steph's Garden and Lawn Service
Steph was working in a client's back garden when her car was broken into out the front and her tools were taken. The stolen gear came to close to $7,000, which was covered under her tools of trade cover.
The names above have been changed for privacy.
Claim process
Claims are when your cover has to earn its premium - and that matters even more when a client is waiting on you to sort it out.
At Viz, your claim is handled by Sedgwick, our specialist claims partner. Their job is to walk you through the process end to end and help get your business back to where it was before the loss, with as little disruption as possible.
1.
Lodge your claim
Get the ball rolling by filling out the claim form online, phoning the claims team on 1300 850 491, or emailing your details to vizclaims@au.sedgwick.com. You'll get confirmation once your information's been received.
2.
A representative will get in touch
Someone from Sedgwick will reach out to gather more information - think a rundown of what happened, a glazier's quote for anything broken, and any other supporting details.
3.
Claim assessment
Once Sedgwick has all the information that they need, they aim to make a decision within 1 to 10 business days - the timeframe depends on how complex the claim is and responsiveness of any third parties (e.g. your client).
Don't leaf your business exposed - join Viz.
Grab a quote online in 2 minutes
Frequently Asked Questions
Gardening and lawn mowing insurance with Viz starts at about $30 a month for $5 million of public liability cover, or about $40 a month for $10 million. Your exact premium depends on your cover limit, the number of workers in your business and your state. Paying monthly comes at no additional cost - no extra fees or interest.
In most cases, yes. Head landscapers, grounds maintenance companies and principal contractors typically require subcontract gardeners to hold current public liability insurance. Most will specify a minimum limit of $10 million or $20 million.
Seconds. Your Certificate of Currency is emailed to you the moment you buy your policy, so you can forward it to a strata manager or agent before you start the job. You can also add it to your phone's digital wallet with the Viz Tradie Pass, which gives you access to your up-to-date Certificate of Currency on demand.
If weedkiller or another spray you're using as a part of your covered business activities drifts and damages plants on a client's or a neighbour's property, it can be covered under your public and products liability insurance. Damage to a third party's property is what the policy is designed to respond to.
Public liability insurance is strongly recommended, and often required, for gardeners and lawn mowing businesses in Australia. Strata managers, real estate agents and commercial clients typically require cover before work starts. It's designed to cover the costs of third party injury or property damage claims that arise from your covered business activities.
Yes. A stone thrown from your mower, brushcutter or edger that accidentally breaks a window or a pool fence panel is third party property damage. Your Viz public liability policy is designed to cover that claim, including legal costs and compensation. Subject to policy terms and conditions.
No. Viz treats gardening, lawn mowing and landscaping as one occupation. Select 'gardening, landscaping and lawn mowing' when you get a quote and all three sit under the one policy, on one premium, with all three listed on your Certificate of Currency.
As a general rule across the Australian insurance industry, you can't insure things that aren't yours. If a mower or labourer you bring on has their own ABN, it's their responsibility to hold their own insurance.
Things to know
Monthly Payments vary by state due to state-based stamp duty charges. Viz charge an annual $25 Policy Fee + $2.50 GST payable in addition to your premium. The prices shown are based on selecting a $500 excess and are an indication only. Your premium will be calculated based on the information you provide to us during the insurance application process.
You can add up to two occupation categories on to your quote online. Some of these categories contain two different trades, e.g. 'Landscaping and renovations'. If you need additional business activities covered or have any questions about our policies, give us a call on 1300 216 226 or email us at hello@vizinsurance.com.au.